Best GST Notice Handling Services in Delhi
Most GST disputes are not lost on the law. They are lost on the calendar.
Under the GST law, a notice is treated as served the moment it is uploaded to your account on the common portal. Nobody has to knock on your door, and nobody has to confirm that you read it. The reply clock starts on the department’s server — not on the day your accountant finally logs in. That single fact is why so many Delhi businesses first learn about a demand when the amount is already sitting in their electronic liability ledger, or when a customer calls to say their input tax credit has been reversed.
If you run a business in Delhi — a trading firm in Chandni Chowk, an IT services company in Nehru Place, a manufacturing unit in Bawana, an exporter in Okhla, or a startup in Connaught Place — the odds of receiving at least one GST communication in a financial year are now uncomfortably high. Data-driven scrutiny, automated return matching and tighter portal controls have made notices a routine part of doing business rather than a rare event.
This guide explains, in plain language, what each GST notice actually means, how much time you get, what a strong reply looks like, and how professional GST notice handling services in Delhi can turn a threatening demand into a closed file. It is written for business owners and finance managers, not for lawyers — so you will find timelines, forms and practical steps rather than long quotations from the statute.
Why Delhi Businesses Are Receiving More GST Notices in 2026
The GST system has moved from self-declaration to near-continuous verification. Several changes have converged, and each one creates a fresh trigger for a notice.
1. Returns are now matched by machine, not by memory. Your GSTR-1, GSTR-3B, GSTR-2B, GSTR-9/9C, e-way bills, e-invoices, ICEGATE import data, TDS/TCS credits and even income-tax turnover are compared automatically. Any gap — even a genuine timing difference — can generate a scrutiny notice without a human ever forming an opinion about your business.
2. Input tax credit is the single biggest battleground. Credit claimed in GSTR-3B beyond what appears in GSTR-2B is the most common reason for a notice. Suppliers who file late, file wrong GSTINs, or do not file at all leave the recipient carrying the burden of proof.
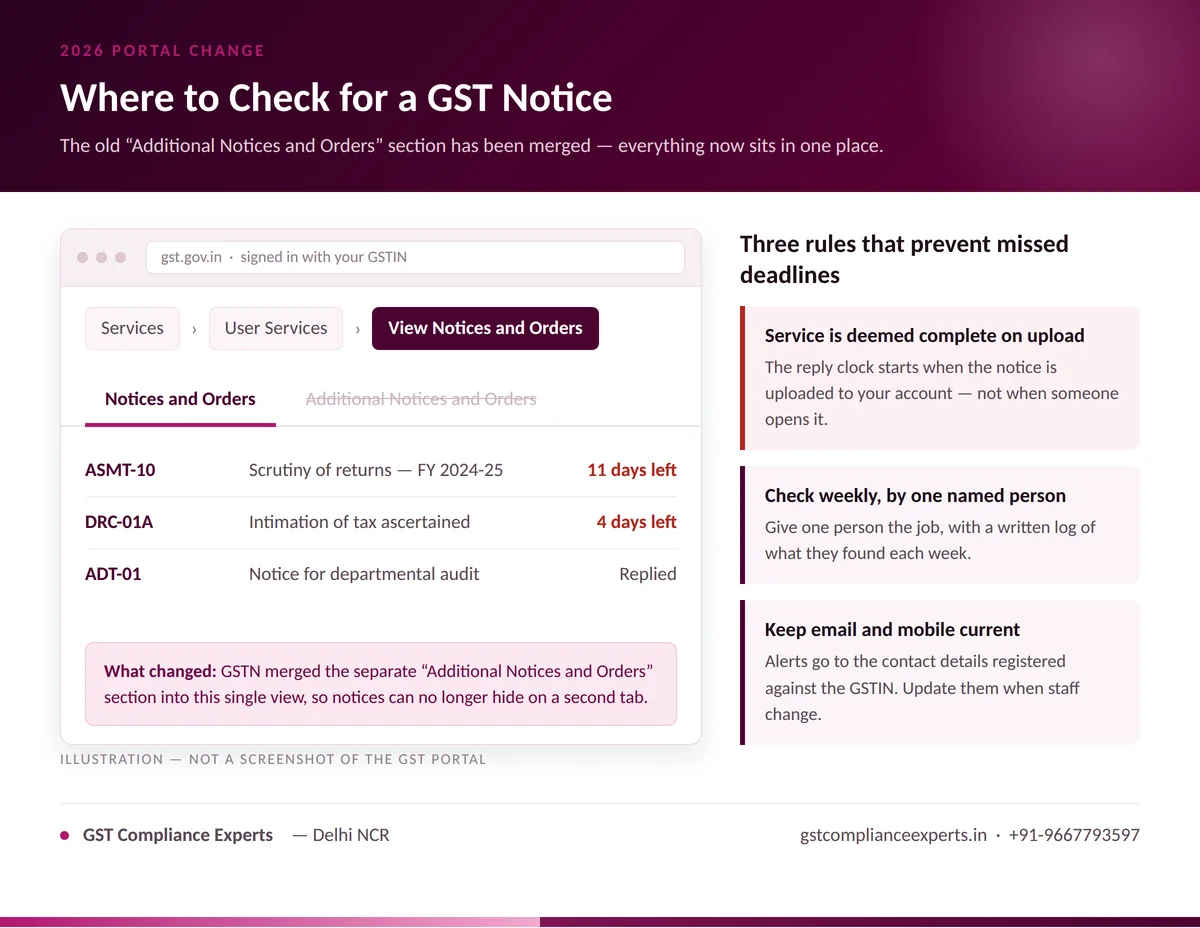
3. The portal itself has tightened — and so has the excuse for missing a notice. Auto-population of outward supply figures in GSTR-3B from GSTR-1/GSTR-1A leaves far less room to “adjust” a return later; corrections must be made in the outward return itself. Returns also become time-barred on the portal after three years from their due date, so an old gap can no longer be quietly regularised — it goes straight into demand territory. And GSTN has now merged the old “Additional Notices and Orders” section into a single Notices and Orders view, so every communication lands in one place. That change was made to stop taxpayers from missing notices — which also means “I didn’t see it, it was on the other tab” no longer works as an explanation before an adjudicating officer.
4. A unified demand provision is now in force. For FY 2024-25 onwards, Section 74A of the CGST Act replaces the earlier split between Section 73 (non-fraud) and Section 74 (fraud) for issuing demands. The fraud/non-fraud distinction still affects penalty, but it is now examined during adjudication rather than being locked in at the notice stage.
5. The appellate machinery has opened up. With the GST Appellate Tribunal (GSTAT) now functioning — its Principal Bench sits in New Delhi — the backlog of unresolved appeals has started moving, and the government has notified extended windows for filing appeals against older orders. Matters that businesses had mentally written off are becoming live again.
The practical takeaway for a Delhi business is simple: notices are no longer exceptional, and the quality of your first reply usually decides whether the matter ends there or turns into three years of litigation.
Types of GST Notices: What Each Form Actually Means
Understanding the form number at the top of the notice is the fastest way to gauge how serious it is. Here is a working map of the notices Delhi businesses see most often.
| Form | What it is | Typical trigger | Usual response time |
|---|---|---|---|
| GSTR-3A | Default notice for non-filing of returns | GSTR-1, GSTR-3B, GSTR-4 or GSTR-9 not filed | 15 days to file the pending return |
| ASMT-10 | Scrutiny notice pointing out discrepancies in a return | GSTR-1 vs GSTR-3B, GSTR-2B vs 3B ITC, turnover mismatch | Usually 30 days; reply in ASMT-11 |
| CMP-05 | Notice questioning eligibility for the composition scheme | Turnover or supply type appears outside composition limits | 15 days; reply in CMP-06 |
| REG-03 | Query on a registration or amendment application | Documents unclear, address proof weak, PPOB doubts | 7 working days; reply in REG-04 |
| REG-17 | Show cause notice for cancellation of registration | Continuous non-filing, no business at declared premises, fake invoicing suspicion | 7 working days; reply in REG-18 |
| REG-23 | Notice after revocation application | Department not satisfied with revocation request | 7 working days; reply in REG-24 |
| ADT-01 | Notice of departmental audit under Section 65 | Selection for audit of records for a period | Records to be produced within 15 days |
| DRC-01A | Intimation of tax ascertained before a formal SCN | Officer’s pre-notice view of short payment | Part B reply; a genuine chance to settle early |
| DRC-01 | Show cause notice raising a formal demand | Scrutiny, audit, investigation or ITC mismatch conclusion | 30 days; reply in DRC-06 |
| DRC-07 | Summary of order creating a demand in the ledger | Adjudication completed | Pay, or appeal within 3 months in APL-01 |
| DRC-13 / DRC-16 | Recovery from third parties, attachment of property | Confirmed demand unpaid | Immediate action required |
| RVN-01 | Notice by the Revisional Authority | Order considered erroneous and prejudicial to revenue | As specified in the notice |
| Summons (Section 70) | Attendance and documents required by an officer | Investigation, intelligence-based enquiry | Date stated in the summons |
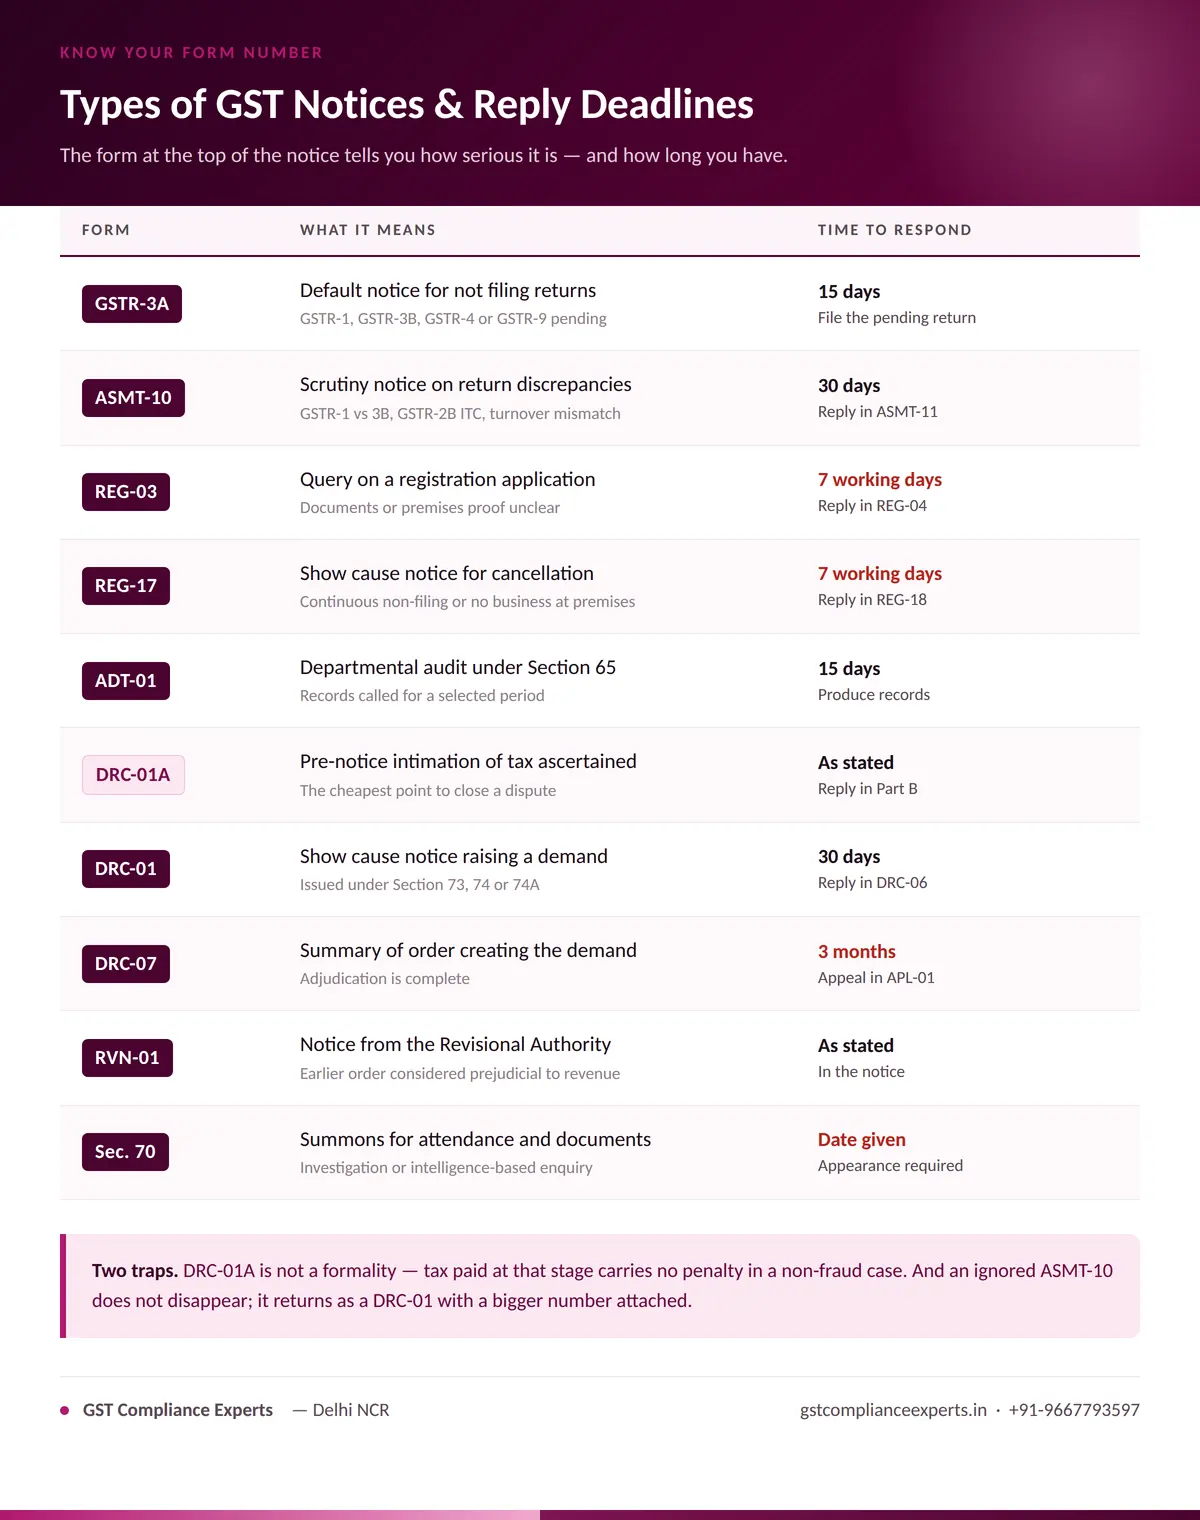
Two points that catch people out. First, an intimation in DRC-01A is not a formality — it is the cheapest point at which a dispute can be closed, because tax paid at that stage attracts no penalty in a non-fraud case, and interest exposure stops growing. Second, an ASMT-10 that is ignored does not go away; it usually reappears as a DRC-01 with a bigger number attached.
Sections 73, 74 and 74A: How Much Time the Department Actually Has
Business owners often ask whether a notice for an old year is even valid. The answer depends on the year involved.
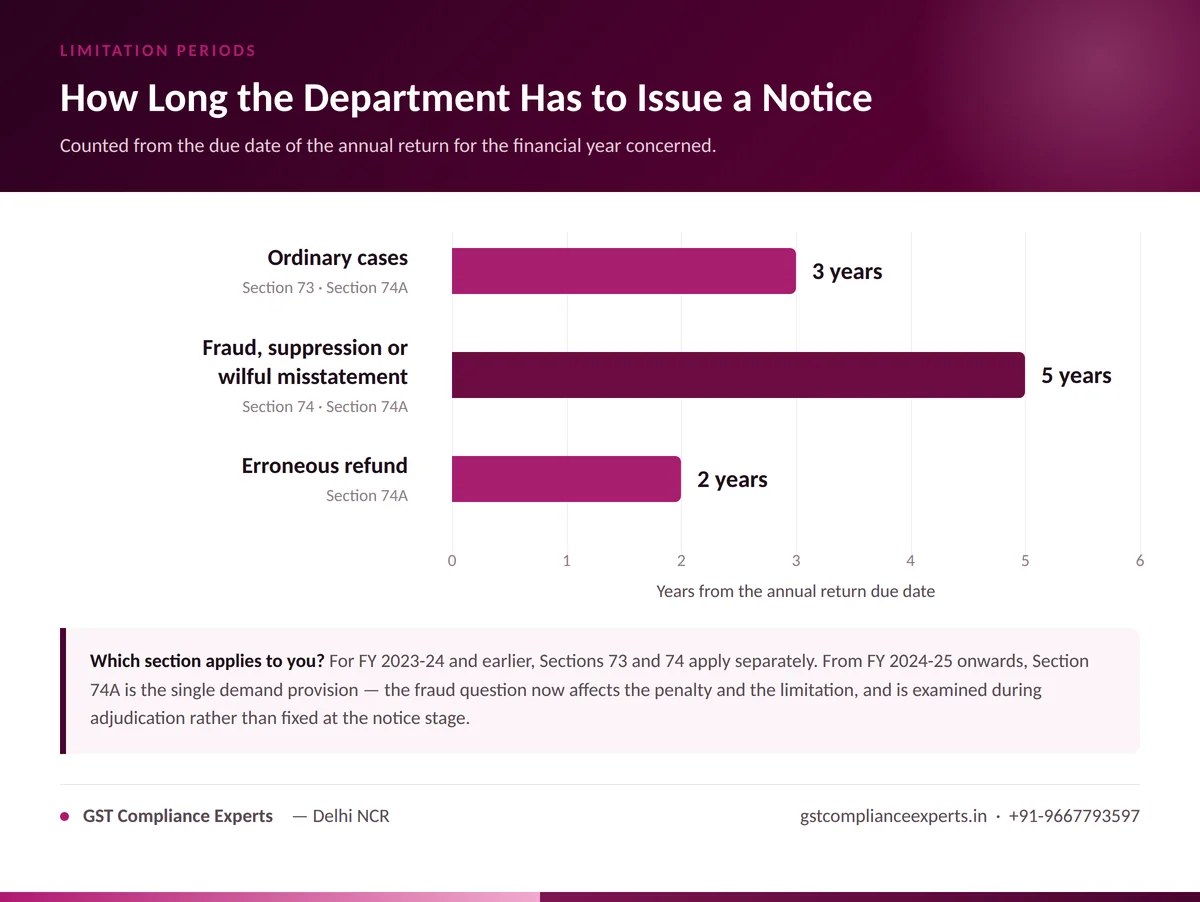
- FY 2023-24 and earlier — Section 73 governs cases without fraud or wilful misstatement, with a show cause notice issuable within three years of the annual return due date. Section 74 governs fraud, suppression or wilful misstatement, with a five-year window.
- FY 2024-25 onwards — Section 74A applies to all demands. The limitation is broadly three years from the annual return due date in ordinary cases and five years where fraud or wilful misstatement is alleged, with a shorter window for erroneous refunds. The notice must be issued a fixed number of months before the last date for passing the order, which is why departments cluster notices near the deadline.
Section 74A also gives taxpayers longer to close a matter voluntarily at a reduced penalty than the earlier provisions allowed. That extra breathing room is only useful if somebody reads the notice, computes the exposure honestly and advises on whether to fight or fold — which is precisely the judgement a GST notice consultant in Delhi is engaged for.
What Happens If You Ignore a GST Notice
There is no scenario in which silence improves the outcome. The realistic consequences, in the order they usually arrive:
- An ex parte order. The officer decides on the material available, which is the department’s own data, and confirms the demand in full.
- Interest and penalty stack up. Interest runs on the tax; penalty follows the section invoked. What began as a modest ITC mismatch becomes a multiple of the original amount.
- Registration risk. Persistent non-response, particularly to REG-17, ends in cancellation — which stops your customers from claiming credit and effectively stops the business.
- Recovery action. Once a demand is confirmed and the appeal window closes, bank accounts can be attached and debtors directed to pay the department instead of you.
- A weaker appeal. Grounds not raised, and evidence not filed, at the adjudication stage are much harder to introduce later. An appeal also requires a pre-deposit of a percentage of the disputed tax, so the cost of a late fight is real cash out of the door.
The cheapest litigation is the one that ends at the reply stage. That is the core argument for professional GST notice reply services rather than a hurried in-house response.
How We Handle a GST Notice: Our 7-Step Process
Good GST notice handling services in Delhi are not about writing a clever letter. They are about process. Every notice we accept goes through the same disciplined sequence, because the department’s file will permanently contain everything we say.
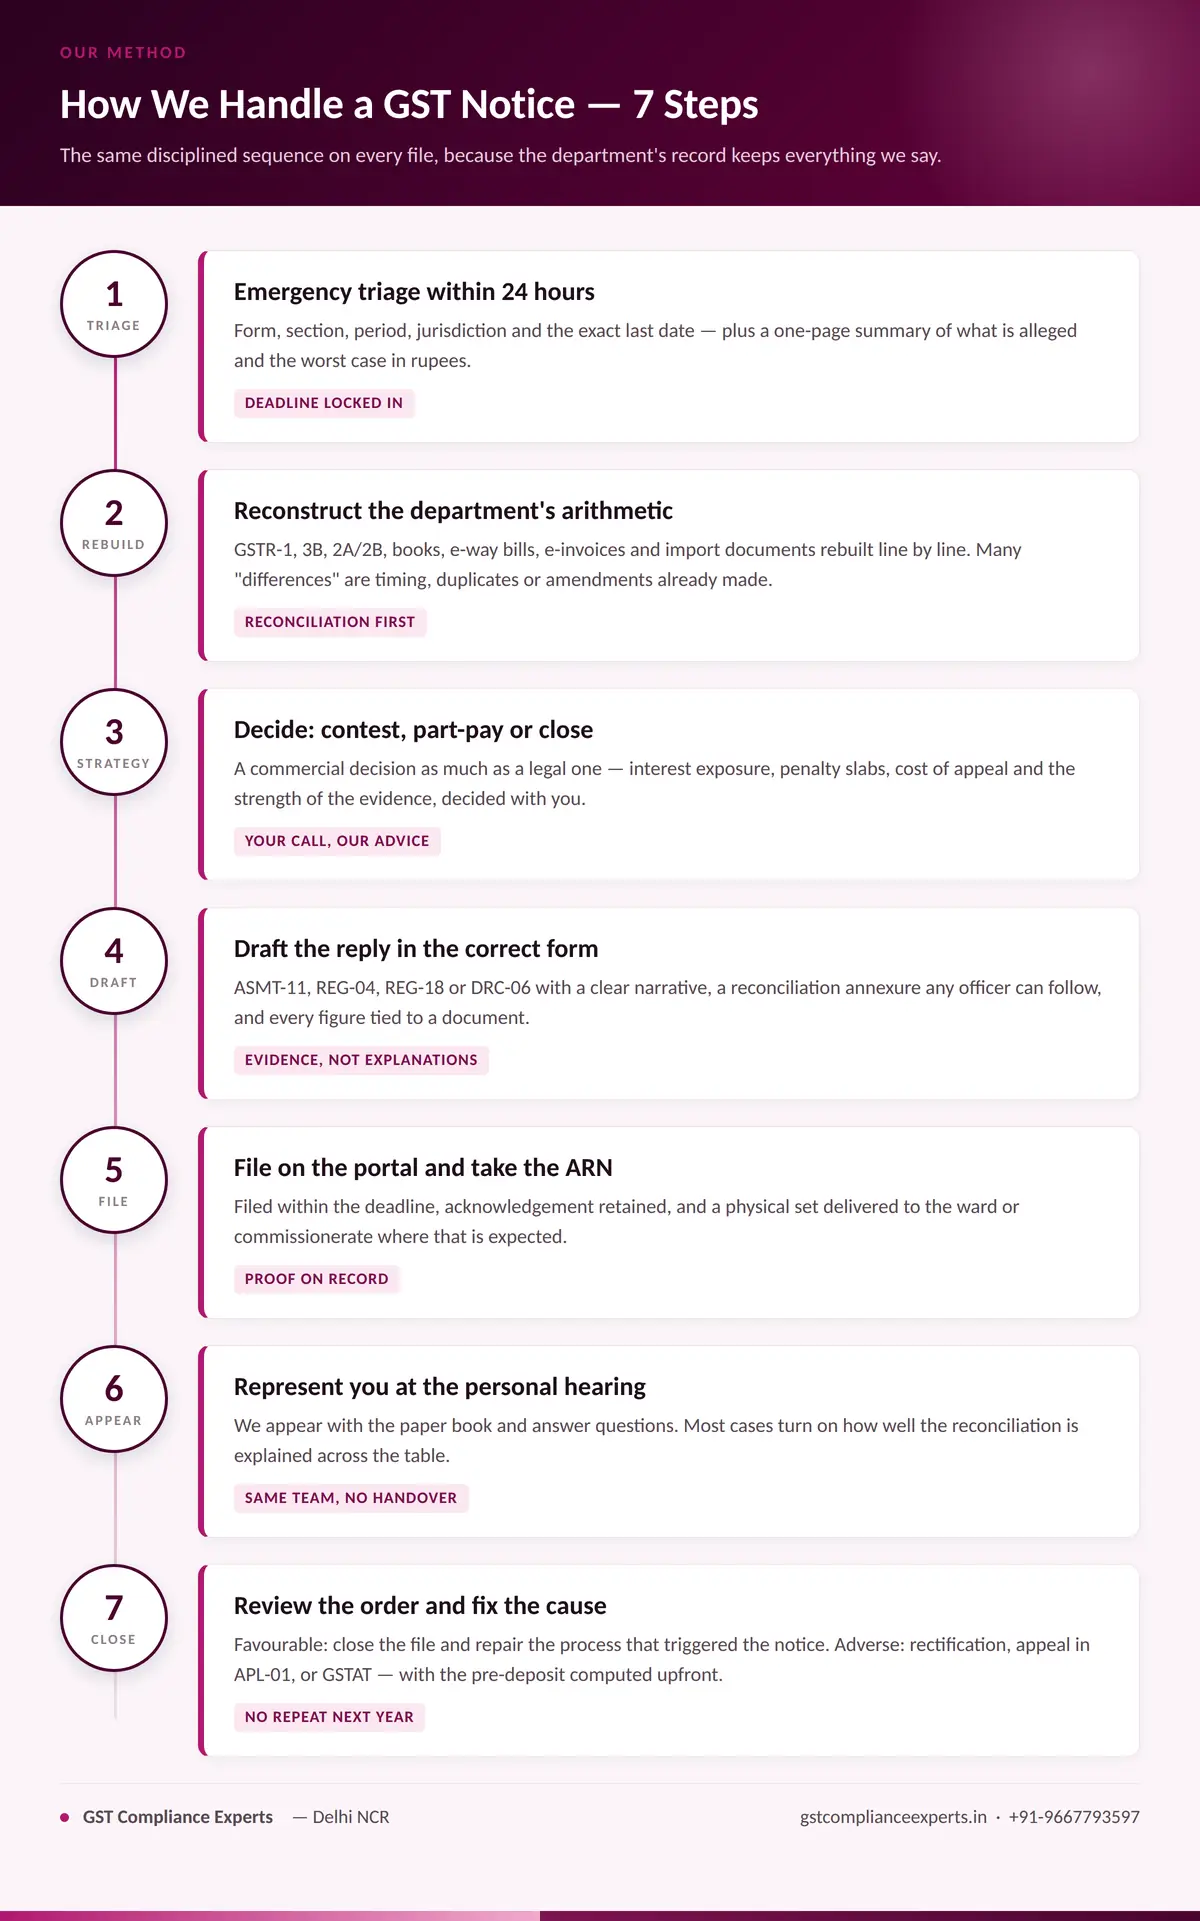
Step 1 — Emergency triage (within 24 hours)
We identify the form, the section, the period, the officer, the jurisdiction (State GST or CGST) and the exact last date for reply. You receive a one-page summary telling you what has been alleged and what the worst case looks like in rupees.
Step 2 — Reconstructing the department’s arithmetic
We rebuild the officer’s calculation from your own records: GSTR-1, GSTR-3B, GSTR-2A/2B, books, e-way bills, e-invoices, import documents and ledgers. In a surprising number of cases the alleged difference is a timing difference, a duplicate, an amendment already made, or credit correctly claimed in a later period.
Step 3 — Legal position and strategy
We decide, with you, whether to contest fully, contest partially, or pay and close. This is a commercial decision as much as a legal one, and it accounts for interest exposure, penalty slabs, the cost of appeal, and the strength of the evidence.
Step 4 — Drafting the reply
The reply is written in the correct form — ASMT-11, REG-04, REG-18, DRC-06 or a formal written submission — with a clear factual narrative, a reconciliation annexure that any officer can follow, and the statutory and judicial support for each ground. Every figure in the reply ties back to a document in the annexure.
Step 5 — Filing and acknowledgement
We file on the GST portal within the deadline, obtain the acknowledgement (ARN), and where the portal or the officer requires it, deliver a physical set to the ward or commissionerate.
Step 6 — Personal hearing and representation
Where a hearing is granted, we appear before the proper officer with the paper book and answer questions on your behalf. Most cases are won or lost on how well the reconciliation is explained across a table, not on how many judgments are cited.
Step 7 — Order review and next steps
When the order arrives, we review it line by line. If it is favourable, we close the file and fix the process that caused the notice. If it is adverse, we advise on rectification, appeal in APL-01 before the Appellate Authority, or an appeal before the GSTAT Principal Bench in New Delhi, along with the pre-deposit required and the realistic prospects.
GST Notice Handling Services We Provide in Delhi
Our GST notice services cover the full life of a dispute, from the first scrutiny query to tribunal-stage representation.
- Scrutiny notice replies (ASMT-10 / ASMT-11) — reconciliation-led responses to GSTR-1 vs GSTR-3B, GSTR-2B ITC, RCM and turnover discrepancies.
- Show cause notice replies (DRC-01, DRC-01A, DRC-06) — detailed submissions on demands raised under Sections 73, 74 and 74A.
- ITC mismatch and blocked credit matters — defending credit where suppliers defaulted, invoices were reported late, or credit was reversed and reclaimed.
- Registration notices (REG-03, REG-17, REG-23) — replies to registration queries, defence against cancellation, and revocation applications with supporting documentation.
- Non-filing and default notices (GSTR-3A) — clearing pending returns, computing late fees and interest, and preventing cancellation.
- Departmental audit support (ADT-01 to ADT-02) — preparing the record set, drafting responses to audit observations, and closing audit paras before they become demands.
- Summons and investigation support (Section 70) — briefing, document preparation and accompaniment for appearances.
- E-way bill, detention and penalty matters — responses under Sections 129 and 130 for goods detained in transit.
- Refund rejection notices (RFD-08 / RFD-09) — replies defending export, inverted duty and excess-payment refund claims.
- Appeals — first appeals in APL-01 before the Appellate Authority and second appeals before the GSTAT, including pre-deposit computation and paper book preparation.
- Post-notice compliance repair — fixing the reconciliation, vendor-follow-up and reporting practices that caused the notice, so the same issue does not return next year.
Notice work sits alongside our other services — GST return filing, GST registration and GST audit and compliance support — because most notices begin as a filing or reconciliation problem, not a legal one.
Why Choose GST Compliance Experts for GST Notice Handling in Delhi
We answer the notice, not the panic. The first thing you get is clarity: what is alleged, what it can cost, and what your realistic options are — before any fee discussion about litigation.
Reconciliation is our default weapon. Most GST demands are arithmetic disputes wearing legal clothing. We win them by producing a reconciliation the officer can verify in ten minutes, backed by source documents.
Delhi jurisdiction knowledge. Delhi businesses are assessed either by the Department of Trade and Taxes (State GST wards) or by the CGST Delhi Zone commissionerates. Procedure, expectations and hearing practice differ. We work with both, across Delhi and the wider NCR — Noida, Gurugram, Ghaziabad and Faridabad.
Deadline discipline. Reply dates are tracked centrally from the day we take a file. We do not seek adjournments to cover our own delays.
One team from notice to tribunal. The person who drafts your reply is the person who appears at the hearing and drafts the appeal, so nothing is lost in handover.
Confidentiality and clean documentation. Your records stay confidential, and every submission we make is one you could show a bank, an auditor or a buyer during due diligence without embarrassment. You can read more about our team or talk to our GST experts directly.
What Delhi Businesses Get Notices For: Five Recurring Patterns
These are the fact patterns we see repeatedly across Delhi’s trading, services and manufacturing sectors. They are illustrative of typical scrutiny, not accounts of specific clients.
Pattern 1 — The supplier who filed late. A Karol Bagh trader claims credit in March on invoices the supplier reports in April. GSTR-2B for March does not show them; ASMT-10 follows. The defence is documentary: invoice, e-way bill, transporter record, bank payment, and the supplier’s subsequent filing.
Pattern 2 — The credit note that was never adjusted. An Okhla manufacturer issues credit notes but the recipient never reverses the credit. The mismatch surfaces on the supplier’s side as an unexplained reduction in outward tax.
Pattern 3 — RCM on the rent. A Nehru Place IT firm pays rent to an unregistered landlord and never discharges reverse charge. The exposure is small each month and large across three years, and it is one of the fastest-growing scrutiny points.
Pattern 4 — The place of supply error. A Connaught Place consultancy bills IGST where CGST/SGST applied, or the reverse. Tax was paid, but to the wrong government — and the department raises a demand for the correct head while the refund of the wrong one has its own limitation clock.
Pattern 5 — The dormant registration. A GSTIN taken years ago for a business that never started attracts GSTR-3A notices, then REG-17. Cancellation is straightforward if handled; if ignored, it blocks the promoter’s future registrations.
GST Appeals in 2026: Deadlines You Cannot Afford to Miss
If an adverse order has already been passed, the clock is different and shorter.
- An appeal to the Appellate Authority under Section 107 is filed in Form APL-01, generally within three months of communication of the order (with a further one month condonable), together with the prescribed pre-deposit of the disputed tax.
- An appeal to the GSTAT under Section 112 is filed after the Appellate Authority’s order, with an additional pre-deposit over and above what was paid at the first stage.
- Pre-deposit is payable through the electronic cash ledger, and admitted tax, interest and penalty must be paid in full separately.
- For orders communicated before 1 May 2026, the government extended the window for filing GSTAT appeals to 31 July 2026; orders communicated on or after that date follow the normal three-month timeline. If you are sitting on an older order, verify your specific dates immediately rather than assuming the extension covers you.
Because these deadlines are jurisdictional, a delay is often fatal to the appeal regardless of how strong the merits are. This is the single most common irreversible mistake we are asked to fix — and frequently cannot.
How Much Do GST Notice Handling Services in Delhi Cost?
Fees for notice work are not one-size-fits-all, and any firm quoting a flat price before seeing the notice is guessing. The realistic drivers are:
- The form and stage — a GSTR-3A default notice is a fraction of the work of a DRC-01 covering three financial years.
- The number of periods and GSTINs involved.
- The volume of reconciliation — a hundred invoices versus a hundred thousand.
- Whether a personal hearing and multiple appearances are required.
- Whether the matter proceeds to appeal, where pre-deposit and paper book work are added.
Our approach is to review the notice first, tell you what is involved, and quote a fixed fee for the defined scope before any work begins. For most scrutiny notices, the professional fee is a small fraction of the demand at stake — and a far smaller fraction of the interest and penalty that accrue if the notice is mishandled.
Five Mistakes That Turn a Small Notice Into a Large Demand
- Replying with an explanation instead of evidence. Officers accept documents, not narratives. Every claim in a reply needs an annexure behind it.
- Admitting more than necessary. Loose wording in a first reply — “the credit was wrongly availed” — is quoted back in the order and in every subsequent stage.
- Waiting to be told. Service is complete when the notice is uploaded to the portal, so the deadline runs whether or not anyone logs in. With everything now consolidated under a single Notices and Orders view, there is one place to check — so give one named person the job of checking it every week and recording what they found.
- Treating DRC-01A as junk mail. It is the cheapest exit available in the entire process.
- Not fixing the root cause. Reply, win, and then repeat the same reporting error next year — and the next notice arrives with a worse compliance history attached.
Frequently Asked Questions About GST Notices
What is a GST notice?
A GST notice is a formal communication from the state or central GST authority pointing out a discrepancy, seeking information, proposing a demand, or asking why an action such as cancellation of registration should not be taken. It is issued in a prescribed form and carries a specific reply deadline.
How do I check if I have received a GST notice?
Log in to the GST portal and open Services → User Services → View Notices and Orders. GSTN has merged the former “Additional Notices and Orders” section into this single view, so all notices, orders and intimations now appear together. Notices are also sent to the email address and mobile number registered against your GSTIN, so keep both current and check the portal weekly — the reply period runs from the date the notice is uploaded, not the date you open it.
How many days do I get to reply to a GST notice?
It depends on the form. Registration-related notices such as REG-03 and REG-17 typically allow seven working days; scrutiny notices in ASMT-10 usually allow thirty days; show cause notices in DRC-01 generally allow thirty days from service. Always follow the date stated in the notice itself.
Can I reply to a GST notice myself?
Legally, yes. Practically, a reply is a legal submission that will be quoted in the order, in appeal and possibly before the tribunal. If the amount is meaningful or the allegation touches fraud, suppression or fake invoicing, professional drafting is worth many times its cost.
What happens if I miss the deadline to reply?
The officer can proceed ex parte and confirm the demand. Your remedies then narrow to rectification, appeal with pre-deposit, or in limited circumstances a writ petition. Acting immediately after realising the lapse still matters — some officers will accept a delayed reply before passing the order.
Do I have to pay the amount mentioned in a show cause notice?
No. A show cause notice is a proposal, not a determination. You are entitled to reply, produce evidence and be heard before any liability is confirmed in an order.
What is the difference between DRC-01A and DRC-01?
DRC-01A is a pre-notice intimation of the officer’s ascertainment, giving you a chance to pay or explain before a formal notice. DRC-01 is the show cause notice itself, which begins formal adjudication.
Are notices from the State GST department and the CGST department different?
The law is the same, but the jurisdiction, portal workflow and hearing practice differ. In Delhi, a taxpayer is assessed either by the Department of Trade and Taxes or by a CGST Delhi Zone commissionerate, and a notice from the wrong authority for the same period and issue is itself a ground of objection.
Can a cancelled GST registration be restored?
Often, yes. Revocation is applied for in Form REG-21, and pending returns, late fees and interest generally have to be cleared first. If the revocation window has passed, an appeal may still be available. The sooner it is taken up, the better the prospects.
Why should I hire professional GST notice handling services in Delhi?
Because the reply becomes part of the record. A well-drafted, evidence-backed reply filed on time can close a matter at the scrutiny stage for a fraction of the demand at stake. A weak reply invites a confirmed demand, interest, penalty and an appeal that requires a cash pre-deposit before it is even heard.
Do you handle GST notices for businesses outside Delhi?
Yes. Notice and appeal work is largely document-driven and portal-based, so we act for clients across Delhi NCR and other states, with physical appearances arranged where a hearing requires it.
How long does a GST notice matter take to close?
A straightforward scrutiny notice can be closed within weeks of filing the reply. An adjudication matter with hearings typically runs a few months. Appeals take longer, and tribunal timelines depend on the bench’s cause list.
Received a GST Notice? Talk to a GST Notice Consultant in Delhi Today
The worst thing you can do with a GST notice is put it in a drawer and hope the officer forgets. The best thing you can do is get it reviewed on the day it arrives, while every option is still open — including the cheap ones.
Send us the notice and we will tell you, without obligation, what it means, what it can cost, and what we would do about it. That is what practical GST notice handling services in Delhi should look like — clarity first, paperwork second, and a deadline that is never missed.
GST Compliance Experts — Delhi NCR
Phone: +91-9667793597
Email: info@gstcomplianceexperts.in
WhatsApp: Message us on WhatsApp
Same-day review of GST notices. Reply drafting, representation and appeals across Delhi, Noida, Gurugram, Ghaziabad and Faridabad.
Disclaimer: This article is for general information as of September 2026 and is not legal advice. GST provisions, forms and timelines change through notifications and circulars, and the correct course of action depends on the facts of each case and the exact wording of the notice received. Please consult a qualified professional before acting.
Related GST Compliance Guides
Detailed notes on the surrounding areas of GST compliance:
- GST Notice Reply for E-Commerce Sellers
- Types of GST Notices – SRC, SCN, DRC, and Others
- How to Read a GST Show Cause Notice (SCN)
- What Is a GST Notice and Why Is It Issued?
- Time Limit to Reply to GST Notice
- GST Compliance for Import-Export Businesses: Complete Guide 2026-27
- GST Compliance for Online Service Providers: Complete Guide 2026
- How to File GSTR‑3B for Startups: GST Return Filing Guide for Delhi NCR & Across India
- GST Compliance for Composite and Mixed Supplies: Complete Guide 2026-27
- GST Compliance for Small Retailers and Traders
- Types of GST Returns in India (GSTR‑1, GSTR‑3B, GSTR‑9, etc.)
- GST Reconciliation Between Books and GST Portal: Complete Guide
- How to Reconcile Sales and GST Returns: Complete Guide
- GST Compliance for Professionals (CA, Lawyers, Doctors, Consultants)
- Difference Between GSTR-1 and GSTR-3B
- GST Return Filing Deadlines Shifted – What Businesses Must Know Now
- GST and Income Tax Compliance Together – Best Practices
- GST Compliance for Software and SaaS Businesses
- GST Return Filing Basics for Beginners
- Common Mistakes in GST Return Filing and How to Avoid Them
- GST Compliance for E‑Commerce Platforms (Amazon, Flipkart, etc.)
